890 Capital September 2026 Investor Update: Charleston Prices Hold, Inventory Builds
The buses are running again and the carpool line is back, and this year that lands a little differently around here. Between us, Caleb and I have added four new daughters in the last three years. Four. We laugh about being outnumbered, and then one of us says the word "weddings" out loud and the laughing stops. Across our two families we are now looking at the whole span at once: daycare, braces, a first car, college tuition, and eventually a few receptions. You have your own version of that list, and it is what capital is actually for.
So here is our September 2026 update. The Charleston real estate market turned in a steady July, with prices holding across the tri-county area while inventory continued to build. Below you will find the July market numbers, our fund snapshot, a direct look at how a self-directed IRA can hold a private real estate note, a recap of last month's investor event, and an invitation to the next one.
Charleston real estate market spotlight: prices hold, inventory builds (July 2026)
July was a quieter month than June, and the tri-county market split three ways. Charleston County kept doing what it has done all year: 557 single-family homes closed, up 6.3% over July 2025, with the median sales price at $732,500, up 2.4%.
| County (single-family detached) | Median | YoY | Closed sales (YoY) | Days on market |
|---|---|---|---|---|
| Charleston | $732,500 | +2.4% | 557 (+6.3%) | 42 |
| Berkeley | $420,975 | −0.9% | 410 (−3.8%) | 40 |
| Dorchester | $422,700 | +5.7% | 269 (−11.2%) | 47 |
Berkeley County cooled slightly on both counts, with closings off 3.8% and the median down 0.9% to $420,975. Dorchester County's median jumped 5.7% to $422,700 on 11.2% fewer sales, which reads as a mix effect more than a price surge: fewer homes closed, and larger ones.
The regional picture is steady rather than hot. Across the full Charleston Trident MLS the median came in at $449,918, up 4.6%, on 1,698 closed sales, down 1.8%. Inventory rose 4.7% to 5,697 homes and months of supply sits at 3.6. Days on market ran 40 to 47 across the three counties, still inside two months. Year to date, the Charleston County median stands at $725,000, up 3.6% over 2025.
What July's Charleston housing data means for a private lender
For a short-term real estate lender, more inventory alongside steady prices is a reasonable place to work. Buyers are still showing up, finished product still sells inside two months, and a slower absorption rate is exactly why we underwrite to a conservative share of after-repair value and keep loan terms short.
Source: Charleston Trident Association of REALTORS®, Local Market Update, July 2026, current as of August 7, 2026. Single-family detached, July year-over-year. Year-to-date medians: Charleston $725,000 (+3.6%), Berkeley $420,000 (+0.6%), Dorchester $399,956 (+0.5%).
Your self-directed IRA can hold a private real estate note
Most people's retirement money sits in an account that only knows how to buy public securities. That is a custodian limitation, not a tax-code limitation. A self-directed IRA can hold a private mortgage note, and for an investor who wants a stated rate instead of a market outcome, that changes what retirement capital is able to do.
Why an IRA is a good home for a real estate note
Interest income is generally not UBIT-taxable. An IRA that lends money and collects interest typically owes no unrelated business income tax. The interest arrives whole.
Rollovers are not capped. Contributions are. The 2026 IRA contribution limit is $7,500, or $8,600 if you are 50 or older. Moving an existing IRA or an old 401(k) has no dollar limit at all. For most investors that is the difference between a $7,500 decision and a real allocation.
It compounds without the annual drag. Payments stay inside the IRA. Tax-deferred in a Traditional, tax-free in a Roth.
How to move IRA funds into a real estate note
- Open or use a self-directed IRA. Forge Trust, or the custodian you already have.
- Transfer, do not withdraw. Custodian-to-custodian avoids the 60-day rule.
- Review the offering documents. The PPM, a sample note, and a recent investor statement.
- Fund your note. Interest accrues at close and is paid monthly to your IRA.
Current 890 Capital note terms are 10.00% for one year, 10.50% for three years and 10.75% for five years, paid monthly by wire or ACH, direct to the IRA. Zero investor fees, $100,000 minimum.
One piece of timing. Custodial transfers take two to four weeks to settle, and we raise against loans we are about to close rather than sitting on idle cash. Investors already in process fill the next window, so start the transfer before the allocation rather than after.
We have done this with about a dozen investors now, so none of it is new to us. We know which forms each custodian wants, where the process tends to stall, and we work with the custodian directly so you are not the one chasing signatures. On your end it is a short stack of paperwork and a phone call.
890 Capital does not provide tax or legal advice. Consult your own advisors on IRA eligibility, prohibited transactions and tax treatment. 890 Capital is not affiliated with Forge Trust or The Charles Schwab Corporation.
890 Capital fund snapshot, September 2026
| Fund inception | April 2024 |
| Active loans | 81 |
| Loans completed | 90 |
| Total capital deployed | $59M+ |
| Average loan size | $346K |
| Average after-repair LTV | 70% |
| Average loan length | 5.8 months |
| Unique borrowers | 56 |
| Total investors | 49 |
| Foreclosures to date | 0 |
| Annualized preferred return | 10% to 10.75% |
Every 890 Capital loan is secured by a first-lien position on real property, underwritten to a conservative share of after-repair value, with short terms that keep us close to each project. Figures reflect fund admin records as of September 1, 2026.
Run your numbers against ours
Enter what you have invested and what it is actually returning, and the calculator runs the same dollars three ways: your current portfolio, an 890 Capital note paying monthly, and one accruing to exit. It charts all three over five years and marks the one, three and five year figures. The 890 rate is editable, so if you think we are being optimistic, lower it and look at the gap anyway. For the record, we have paid 10% APY every month since inception in April 2024.

Illustrative only. The calculator does arithmetic on the rates you enter. It is not a projection, an offer, or a guarantee of any return, and figures are gross of taxes and fees. Renewal rates are not guaranteed.
Last month: Capital at Work, inside a borrower's fix-and-flip

In August we held our investor event inside one of our borrower's fix-and-flip projects, and it was a good night. Borrowers, investors who have been with us a while, and a solid group still deciding all stood around the same counter with a drink in hand. Plastic sheeting still on the walls, a serious spread of snacks, and the collateral right there to walk through.
The questions were the good kind: what the numbers actually look like, how the loan is secured, what happens when a timeline slips. Standing in a half-finished house makes those easier to answer honestly.
You're invited: Cocktails & Capital, September 16 in Mount Pleasant
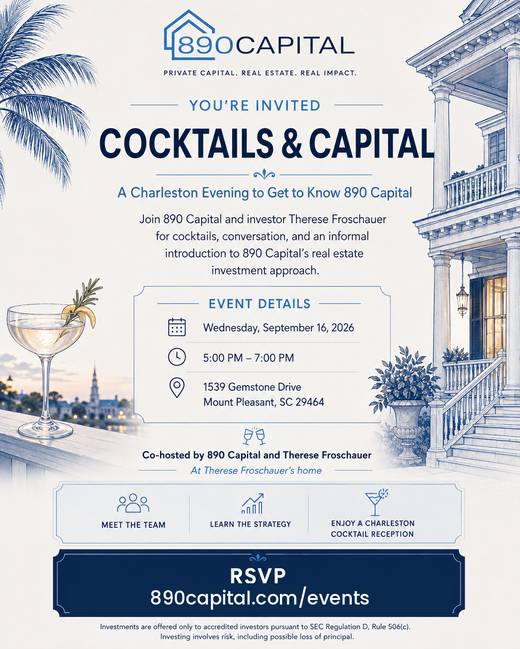
An informal evening at the home of Therese Froschauer, an 890 Capital investor, hosted with our team. Meet the people managing your capital, hear how the strategy actually works, and ask the questions you would not ask on a webinar. Charleston cocktail reception.
Wednesday, September 16, 2026 · 5:00 to 7:00 PM · 1539 Gemstone Drive, Mount Pleasant, SC 29464. Space is limited, so RSVP before the event fills up!
As always - direct, transparent, useful.
- Frank Conway | 890 Capital
890 Capital, LLC · 217 Lucas Street, Unit G, Mount Pleasant, SC 29464 · (843) 620-9890 · 890capital.com
This post is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any security. Investments in 890 Capital, LLC are available only to investors verified as accredited under Rule 506(c) of Regulation D and involve risk, including possible loss of principal. Past performance is not indicative of future results. Stated preferred return targets are not guaranteed. Any offering is made solely through the Private Placement Memorandum and definitive subscription documents, which should be read in full. 890 Capital, LLC is not a registered investment adviser or broker-dealer and does not provide tax or legal advice.