890 Capital August 2026 Investor Update: Charleston Buyers Surge, and a Clean Book

Here is our August 2026 update. The Charleston real estate market had a strong June, with closed home sales surging across all three tri-county markets, and the 890 Capital loan book remains clean, with no defaults and no foreclosures. Below you will find the June market numbers, our fund snapshot, a look at how we manage downside when a project runs long, a note from one of our investors, and an invitation to see the fund up close.

Charleston real estate market spotlight: buyers show up in force (June 2026)

June was a volume story. Closed single-family sales rose in every tri-county market, led by a striking 25.3% jump in Charleston County, where 648 homes changed hands against 517 a year ago.

County (single-family detached) Median YoY Closed sales (YoY) Days on market
Charleston $768,500 +2.5% 648 (+25.3%) 40
Berkeley $415,000 −0.3% 494 (+6.2%) 46
Dorchester $403,208 +0.4% 285 (+8.4%) 43

Prices stayed firm. The Charleston single-family median climbed to $768,500, up 2.5% year over year, while Berkeley and Dorchester held essentially flat at $415,000 and $403,208. Year to date, the Charleston median sits at $725,000, up 3.6% over 2025. Homes are still moving fast, with days on market between 40 and 46 across all three counties, well under two months.

For a lender, this is a healthy backdrop. Demand is deep, prices are steady, and finished product sells quickly, especially in the mid-market where most of our renovation borrowers operate. That is exactly the environment our underwriting is built for.

Source: Charleston Trident Association of REALTORS®, Local Market Update, June 2026. Single-family detached, June year-over-year. Year-to-date medians: Charleston $725,000 (+3.6%), Berkeley $420,000 (+1.1%), Dorchester $396,000 (+0.1%).

Fund snapshot: 890 Capital by the numbers (August 2026)

A transparent look at the fund as of August 1, 2026.

Metric Value
Fund inception April 2024
Active loans 73
Loans funded to date 157
Loans completed 84
Total capital deployed $56M+
Average loan size $357K
Average after-repair LTV 70%
Average loan length (realized) 6.0 months
Unique borrowers 53
Total investors 47
Foreclosures to date 0
Annualized preferred return 10% to 10.75%
Last distribution On time

Preferred return classes: 1-Year 10%, 3-Year 10.5%, 5-Year 10.75%.

Behind the lending: what happens when a deal goes sideways

We have never had a foreclosure, and we intend to keep it that way. But no honest lender will tell you every project runs perfectly. Timelines slip, a rehab hits a surprise, a borrower's buyer falls through. The question that actually protects your capital is not whether anything will ever go wrong, it is what is in place for when it does.

It starts with the collateral. Every 890 Capital loan is secured by a first-lien position on real property, and we lend against a conservative share of the after-repair value, roughly 70% on average across the book. That equity cushion is the margin that lets a loan be made whole even if a property has to be sold in a softer market than the one we underwrote.

Structure does the rest. Loans are short, most around six months, so we are never far from a payoff or a fresh look at a borrower's progress. We service actively, watch draws and timelines, and stay in contact rather than waiting for a maturity date to learn there is a problem. When a project runs long, our first move is almost always a workout: an extension, a modified draw schedule, or a plan to get the property listed and sold. Foreclosure is the last tool, not the first, because a well-secured loan usually resolves faster through cooperation than through a courtroom.

The takeaway for investors is simple. Discipline up front, in the lien position, the loan-to-value, and the loan term, is what turns an occasional bumpy project into a non-event. Zero foreclosures is the result of that design, not luck.

See what your capital could earn: the 890 Capital returns calculator

We built a simple calculator so you can see the numbers for yourself. Choose a note term, set an amount, and decide whether to take monthly income or reinvest. As an illustration, $250,000 in a 1-Year Note at 10%, with returns reinvested monthly, grows to about $276,178 in a single year. Prefer steady income instead? That same note pays roughly $2,083 a month.

890 Capital returns calculator illustration: $250,000 in a 1-year note at 10%, reinvested monthly
Illustration only, not a guarantee or projection. Renewal rates are not guaranteed.

Estimate your return →

Five ways to verify 890 Capital is legitimate

You should never take an investment firm's word for it, including ours. Here is exactly how to verify 890 Capital independently:

  1. Our SEC Form D filing, viewable on EDGAR (Regulation D, Rule 506(c)).
  2. The publicly recorded first-lien deeds of trust securing our loans.
  3. Borrower payment records and a walkthrough of the cash flow.
  4. A segregated 890 Capital, LLC bank account.
  5. Conservative loan-to-value math on every deal.

Real proof, not promises. See all five, with step-by-step instructions to verify each one yourself, at 890capital.com/verify890.

In an investor's own words
Therese, an 890 Capital investor
Therese, an 890 Capital investor.

"Frank was extremely knowledgeable and competent, and being in real estate, I knew of Caleb's work ethic and success. I was compelled because I would be making much more on my investment than my traditional brokerage account was making.

I met with them with a list of detailed questions, and they answered every one in detail. That gave me the confidence to move forward. With five children, the return is fantastic. It helps pay for my son's grad school and, of course, gifts for my grandson. When my personal investment property sells next year, I will definitely be investing more. To receive the same return with passive income is too tempting to pass up."

- Therese, 890 Capital investor

Testimonial from an actual 890 Capital investor who was not compensated for this statement. Individual experiences vary and are not a guarantee of future results.

You're invited: Capital at Work, an inside look at 890 Capital

If you are an accredited investor, join us for an on-site evening to see how capital is deployed, secured by real assets, and positioned to generate returns. We will walk a property, cover how we invest and how we make money, and you will meet the team in person.

Space is limited and invitations are non-transferable.
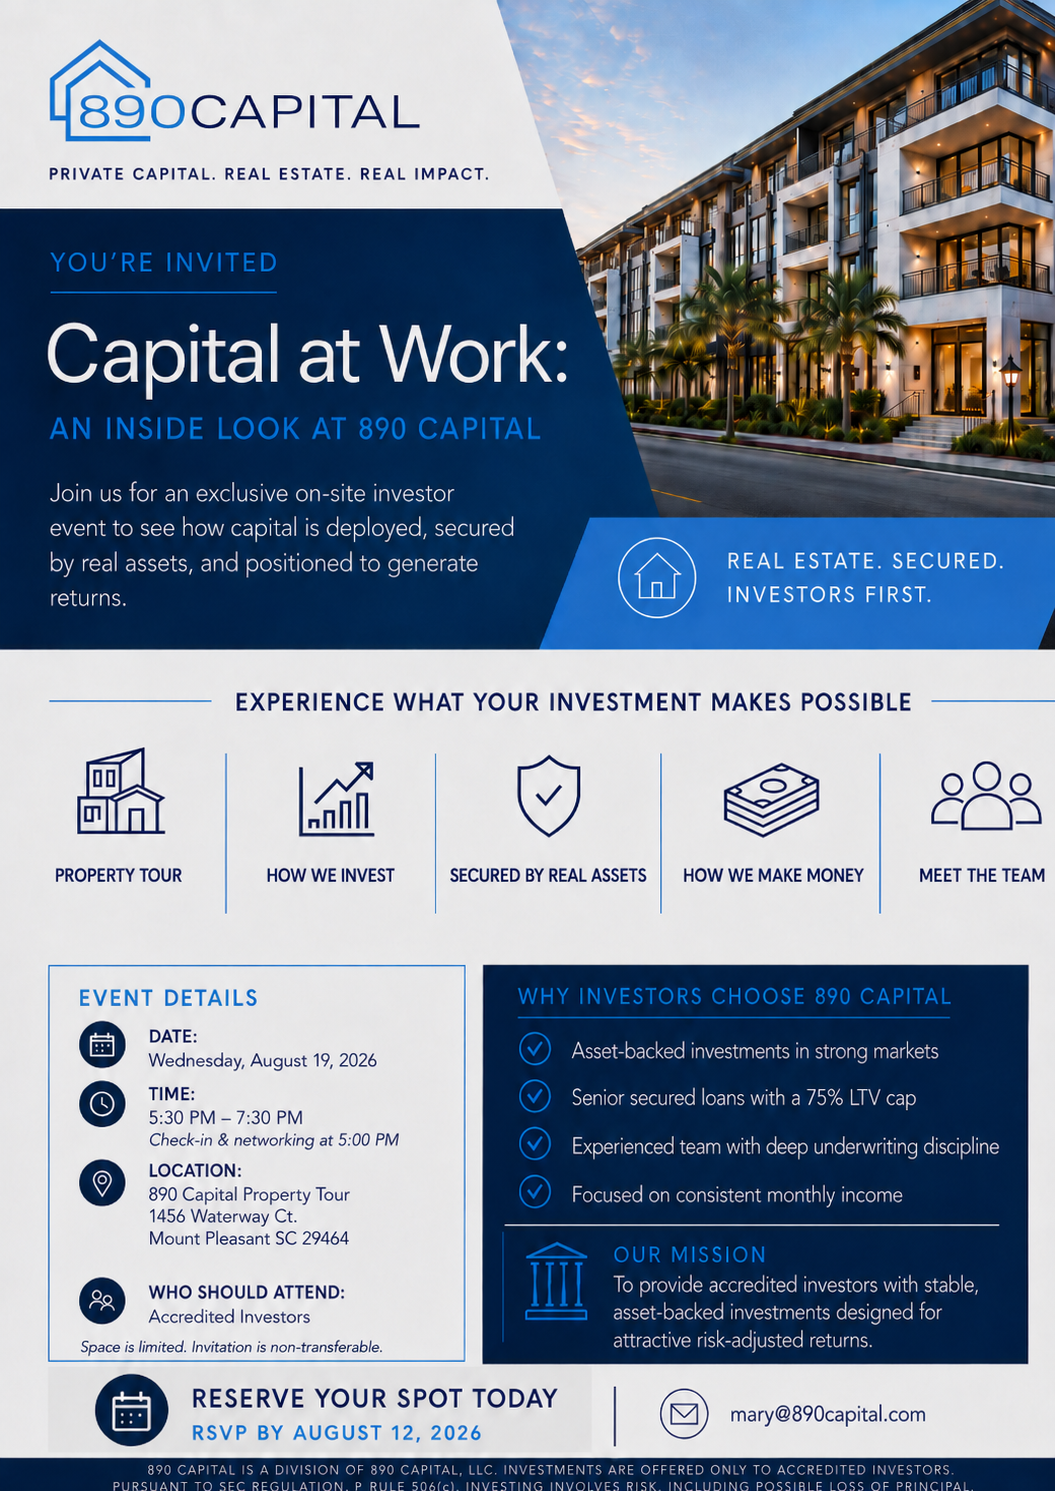
Capital at Work: An Inside Look at 890 Capital - August 19, 2026 accredited-investor event flyer, 1456 Waterway Ct., Mount Pleasant SC

890 Capital, LLC · 217 Lucas Street, Unit G, Mount Pleasant, SC 29464 · (843) 620-9890 · frank@890capital.com · 890capital.com

This article is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any security. Investments in 890 Capital, LLC are available only to accredited investors and involve risk, including possible loss of principal. Past performance is not indicative of future results. Stated preferred return targets are not guaranteed. Any offering is made solely through definitive offering documents. 890 Capital, LLC is not a registered investment adviser or broker-dealer.

How hard money loans are underwritten (and how we say no)

Most of what protects your money at 890 Capital happens before a single dollar goes out the door. It happens in underwriting: the unglamorous, checklist-driven work of deciding which loans we make and, just as often, which ones we turn down.

We get asked how we've stayed at zero foreclosures across 126 loans since inception. The honest answer is that we say no a lot. This is a plain-English look at how hard money loans are underwritten at 890, and the specific reasons a deal doesn't make it.

What underwriting actually means

Underwriting is the process of pricing and stress-testing a loan before you fund it. For a hard money lender, that means answering one question from a lot of angles: if everything goes wrong, does the property still cover the loan?

We are not underwriting the borrower's optimism or the glossy after-photos. We are underwriting the asset, the plan, and the exit. A hard money loan is short-term, secured by real property, and repaid when the borrower sells or refinances. So the property has to carry the loan on its own, today, at conservative numbers.

How hard money loans are underwritten at 890

Every deal we consider runs the same gauntlet before it gets a yes. This is how hard money loans are underwritten here, step by step.

First, position. We take a first-position mortgage on every loan, without exception. If a borrower defaults, first position means we are first in line on the collateral, not standing behind a bank or another lender. It is the single most important protection in the entire structure.

Second, loan-to-value. We cap every loan at 75% loan-to-value, and we routinely underwrite well below it. Our average across the book sits around 66%. That gap between what a property is worth and what we lend against it is the margin of safety.

Third, an independent read on value. We do not take the borrower's number. We pull comparable sales by hand, form our own opinion of current value, and take a conservative view of the after-repair value. A model tells you what a deal should return; standing in the house tells you whether it will.

Fourth, the borrower's track record and liquidity. We want to see that this operator has completed projects like this one and has the reserves to finish if the budget slips. A strong operator with room to maneuver is worth more than a thin file with a great story.

Fifth, the exit. Before we wire anything, we need a credible, funded way for the loan to be repaid: a realistic sale in a market we know, or a refinance the borrower can actually qualify for. No exit, no loan.

How we say no

The checklist above is also a filter, and it screens out more deals than it lets through. A few of the reasons a file gets a no:

The equity cushion is thin. If our loan sits too close to the property's real value, there is no room for us to be wrong, and there is always some chance we are wrong.

The value only works if the market keeps rising. We underwrite to today's comparable sales, not to a forecast. A deal that needs appreciation to pencil is a bet, not a loan.

The borrower is stretched across too many projects at once. Capital and attention are finite. An operator running six simultaneous rehabs is a different risk than one focused on two.

There is no credible, funded exit. If we cannot see how the loan gets paid back, the return does not matter.

It is a property or a submarket we cannot underwrite block by block. We lend only in the Charleston tri-county because we know it street by street. When we cannot form a confident view of value, we pass.

Why the boring version wins

The point of underwriting this way is not to make the most loans. It is to make loans that behave. First-position collateral, a conservative LTV, an independent value, a proven borrower, and a real exit combine into something predictable: monthly distributions paid on time since inception, and zero foreclosures across the book.

Discipline is the product. The deals you never see, the ones we turned down, are as much a part of the track record as the ones we funded. You can read our recent fund updates on the 890 Capital blog to see how that discipline shows up in the numbers over time, and you can learn more about the monthly-income model on our Easy Cashflow page.

A note on who this is for

890 Capital is a private real estate fund available to accredited investors under a Regulation D 506(c) offering. If you are not sure whether you qualify, the SEC lays out the accredited investor definition in plain terms at investor.gov. If you would like to see the full details of the offering and how to participate, you can request investor access.

For accredited investors only. Past performance does not guarantee future returns. See 890capital.com for full disclosures.

890 Capital July 2026 Investor Update: A Strong Spring, a Clean Book, and a Growing Family

From all of us at 890 Capital, we hope you have a safe, happy Fourth of July and a wonderful long weekend. Here is our July 2026 update: the Charleston real estate market rebounded in May, our real estate loan book remains 100% performing, and we have a few pieces of good news to share, including a look at the tri-county numbers, our fund snapshot, and a couple of simple ways to dig deeper.

The headline from June still holds: every active loan in the 890 Capital portfolio is current and performing. No defaults, no foreclosures. We repeat it on purpose, because in private credit a quiet, clean book is the whole point. Reliability is the product.

Charleston real estate market spotlight: the top end bounces back (May 2026)

Last month we flagged a softer top end after Charleston County's single-family median dipped in April. The May 2026 numbers answered the question.

County (single-family detached)MedianYoYClosed sales (YoY)Days on market
Charleston$719,500+6.6%591 (+4.6%)40
Berkeley$422,444-0.6%443 (-11.2%)49
Dorchester$400,000+1.1%288 (+23.1%)39

The Charleston single-family median climbed to $719,500, up 6.6% year over year, with closed sales up 4.6%. The April dip was a single-month wobble, not a trend. Year to date, the county median sits at $716,500, up 3.6% over 2025.

Underneath the headline, the tri-county story is about volume and affordability. Dorchester is the standout: closed single-family sales jumped 23.1% year over year as buyers chase the most attainable price point in the region, a $400,000 median. Berkeley held prices essentially flat while transaction volume cooled, with closings down 11.2%. Days on market stayed tight across all three counties, from 39 in Dorchester to 49 in Berkeley.

For a lender, this is a healthy backdrop. Prices are firm, homes are still selling in well under two months, and demand is deepest in the mid-market where most of our renovation borrowers operate. Well-priced, well-finished product moves. That is the kind of market our underwriting is built for.

Source: Charleston Trident Association of REALTORS®, Local Market Update, May 2026. Single-family detached, May year-over-year. Year-to-date medians: Charleston $716,500 (+3.6%), Berkeley $423,533 (+2.1%), Dorchester $395,000 (+0.3%).

Fund snapshot: 890 Capital by the numbers (July 2026)

A transparent look at the fund as of July 1, 2026.

MetricValue
Fund inceptionApril 2024
Active loans64
Loans funded to date143
Loans completed79
Total capital deployed$51M+
Average loan size$358K
Average after-repair LTV67%
Average loan length (realized)5.8 months
Unique borrowers49
Total investors44
Foreclosures to date0
Annualized preferred return10% to 10.75%
Last distributionOn time

Preferred return classes: 1-Year 10%, 3-Year 10.5%, 5-Year 10.75%.

Behind the lending: why six-month real estate loans are a feature, not a compromise

Most of our loans carry a six-month term, and in practice they pay off even faster, just under six months on average across every loan we have closed. People sometimes assume short loans mean small ambitions. The opposite is true. Short duration is one of the most important risk controls we have, and it is deliberate.

Short loans keep capital moving. Instead of locking money into a five-year position while interest rates, home values, and demand shift around us, we lend, get repaid, and lend again. Every repayment is a fresh chance to re-price risk against current conditions rather than conditions from years ago. That recycling is how a disciplined book stays disciplined.

Short loans also enforce a clear exit. A six-month loan is for a defined project with a defined endpoint, a renovation that gets finished and sold or refinanced, not an open-ended bet on the market drifting higher. The borrower knows the plan, and so do we, before a dollar goes out the door.

For investors, the payoff is flexibility and visibility. We are not asking you to lock up capital for years against an illiquid position. The portfolio turns over steadily, the collateral is real and recent, and the strategy adapts as the market does. Short is not a limitation. It is the design.

See what your capital could earn: the 890 Capital returns calculator

We built a simple calculator so you can see the numbers for yourself. Choose a note term, set an amount, and decide whether to take monthly income or reinvest. As an illustration, $250,000 in a 1-Year Note at 10%, with returns reinvested monthly, grows to about $276,178 in a single year. Prefer steady income instead? That same note pays roughly $2,083 a month.

890 Capital returns calculator illustration: $250,000 in a 1-year note at 10%, reinvested monthly, growing over seven years
Illustration only, not a guarantee or projection. Renewal rates are not guaranteed.

Five ways to verify 890 Capital is legitimate

You should never take an investment firm's word for it, including ours. Here is exactly how to verify 890 Capital independently:

  1. Our SEC Form D filing, viewable on EDGAR (Regulation D, Rule 506(c)).
  2. The publicly recorded first-lien deeds of trust securing our loans.
  3. Borrower payment records and a walkthrough of the cash flow.
  4. A segregated 890 Capital, LLC bank account.
  5. Conservative loan-to-value math on every deal.

Real proof, not promises. See all five, with step-by-step instructions to verify each one yourself, at 890capital.com/verify890. Reach out and we will walk you through any of it.

890 Capital in the press: Moultrie News feature

The Post and Courier's Moultrie News profiled 890 Capital this month in a piece titled "890 Capital bringing investment opportunities to life." It is a good look at why Caleb and I started the company, how we connect investors with short-term real estate projects across the Southeast, and the reputation-based, trust-first way we try to operate in the Lowcountry.

Read the Moultrie News feature on 890 Capital →

Team and community

Welcome to the world, Sutton and Elle

Twin girls Sutton and Elle Pearson, daughters of 890 Capital co-founder Caleb Pearson
Sutton and Elle Pearson.

Caleb Pearson, 890 Capital's co-founder and General Partner, and his wife Ashley welcomed twin girls in May, Sutton and Elle. Caleb, for the record, continues to be happily and thoroughly outnumbered by the women in his house. From all of us, congratulations to the Pearsons.

An evening with investors at Kingstide

This past month we hosted a prospective-investor gathering at Kingstide, bringing together members of the local community for an evening of conversation. It was exactly the kind of night we enjoy most: real questions, honest answers, and the chance to talk through what we do and why.

We walked through how the fund is structured, how we underwrite, and how steady, asset-backed lending can help people build wealth without the volatility or the day-to-day work of owning property. The best part was simply meeting people face to face. If you would like to join us at a future event, get in touch and we will make sure you are on the list.


890 Capital, LLC · 217 Lucas Street, Unit G, Mount Pleasant, SC 29464 · (843) 620-9890 · frank@890capital.com · 890capital.com

This article is for informational purposes only and does not constitute an offer to sell or a solicitation of an offer to buy any security. Investments in 890 Capital, LLC are available only to accredited investors and involve risk, including possible loss of principal. Past performance is not indicative of future results. Stated preferred return targets are not guaranteed. Any offering is made solely through definitive offering documents. 890 Capital, LLC is not a registered investment adviser or broker-dealer.

Why we haven't gated. The structural reason, not the marketing reason.

Several of the largest private credit funds in the country have frozen investor redemptions in the past six months. The headlines read like sudden events. They aren't. They're the visible end of a structural choice the fund made years earlier about what it lends against and how that collateral behaves under stress.

890 Capital has not gated. We never have. And given how we're built, we have no plans to.

The reason is structural, not heroic.

When a fund is built on layered exposure to corporate debt, equity tranches, or pooled investments in operating businesses, the underlying assets can't always be liquidated fast enough to meet investor demand. The fund's cash position is downstream of cap-table negotiations, secondary-market bids, asset sales that take quarters to close. When redemptions surge, the fund either fire-sells at a discount or it gates.

That's the bind. It is rational, and it is also the kind of risk most investors don't price in until the gate is already down.

We are built differently because we lend on a different kind of asset.

Every 890 Capital loan is secured by a first-position deed of trust on real property in the Charleston tri-county. The collateral is the building. Not a promise from a borrower. Not equity in an operating company. Not a slice of a portfolio of receivables. A specific house, on a specific block, with a specific value our team has underwritten.

Three structural facts shape what happens next:

Loans are short. Average loan length across the 890 portfolio is 6.6 months. Capital cycles back to the fund continuously. We don't have to sell anything to free up cash — loans pay off on their own schedule, and the schedule is short.

Loans are first-position. If the worst case happens and a borrower can't perform, we are first in line on the foreclosure. We've never had to test this — zero foreclosures across 126 loans to date — but the line is there.

The collateral is finite and local. The properties we lend against are in markets where Caleb Pearson, our Chief Real Estate Executive, has sold 1,250+ homes and flipped 400+ over fifteen years. Underwriting is done by people who've walked the block. The asset has a buyer at a known number even in a worse market.

Where does that leave us, two years in?

As of June 1, every active loan in the portfolio is current and performing — 53 active loans representing more than $19M in principal. No defaults. No foreclosures.

126 loans funded since inception. 73 paid off. 53 active. $45M+ deployed. Zero foreclosures. Zero gated withdrawals. Every monthly distribution paid on time, every month, since inception in April 2024.

That structural choice doesn't make for exciting marketing copy. It does make for predictable, reliable returns for our accredited investors.

If you're new to 890 Capital and the offering — three terms, 10.00% APY for 1-year, 10.50% for 3-year, 10.75% for 5-year, distributions paid monthly by the 5th, $100K minimum, 506(c) accredited only — the next step is at 890capital.com/request-investor-access.

For accredited investors only. Past performance does not guarantee future returns. See 890capital.com for full disclosures.

Want to talk through whether 890 Capital fits your portfolio?

Request investor access at 890capital.com/request-investor-access